30 Oct 2026 · Chirag Asnani
Market Wrap: Pharma to the Rescue
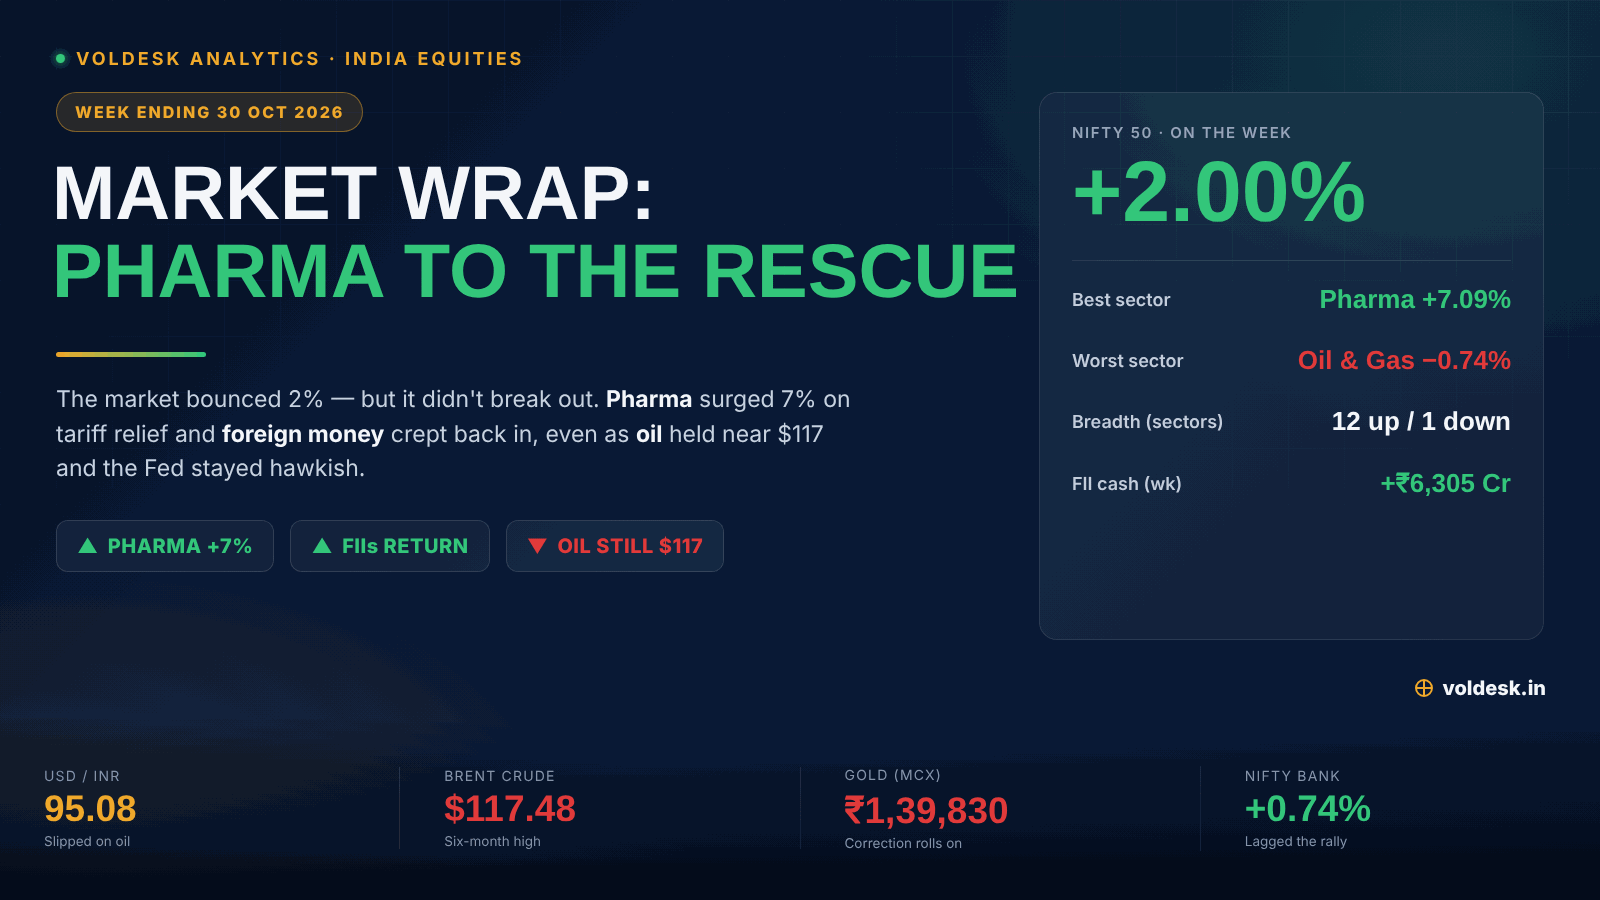
For the third week running, the market moved a lot and went almost nowhere. After The Snapback and The Snapback Fades, this week was the bounce. The Nifty 50 rose 2.00% to 23,053, taking back the 23,000 mark it had lost a week earlier. Over the fortnight it is still down 0.40%, so the autumn range we have been describing for three weeks holds. What was different this week was the reason the market could rise at all. Oil didn't cool. Pharma came to the rescue instead.
Sectors — the tape
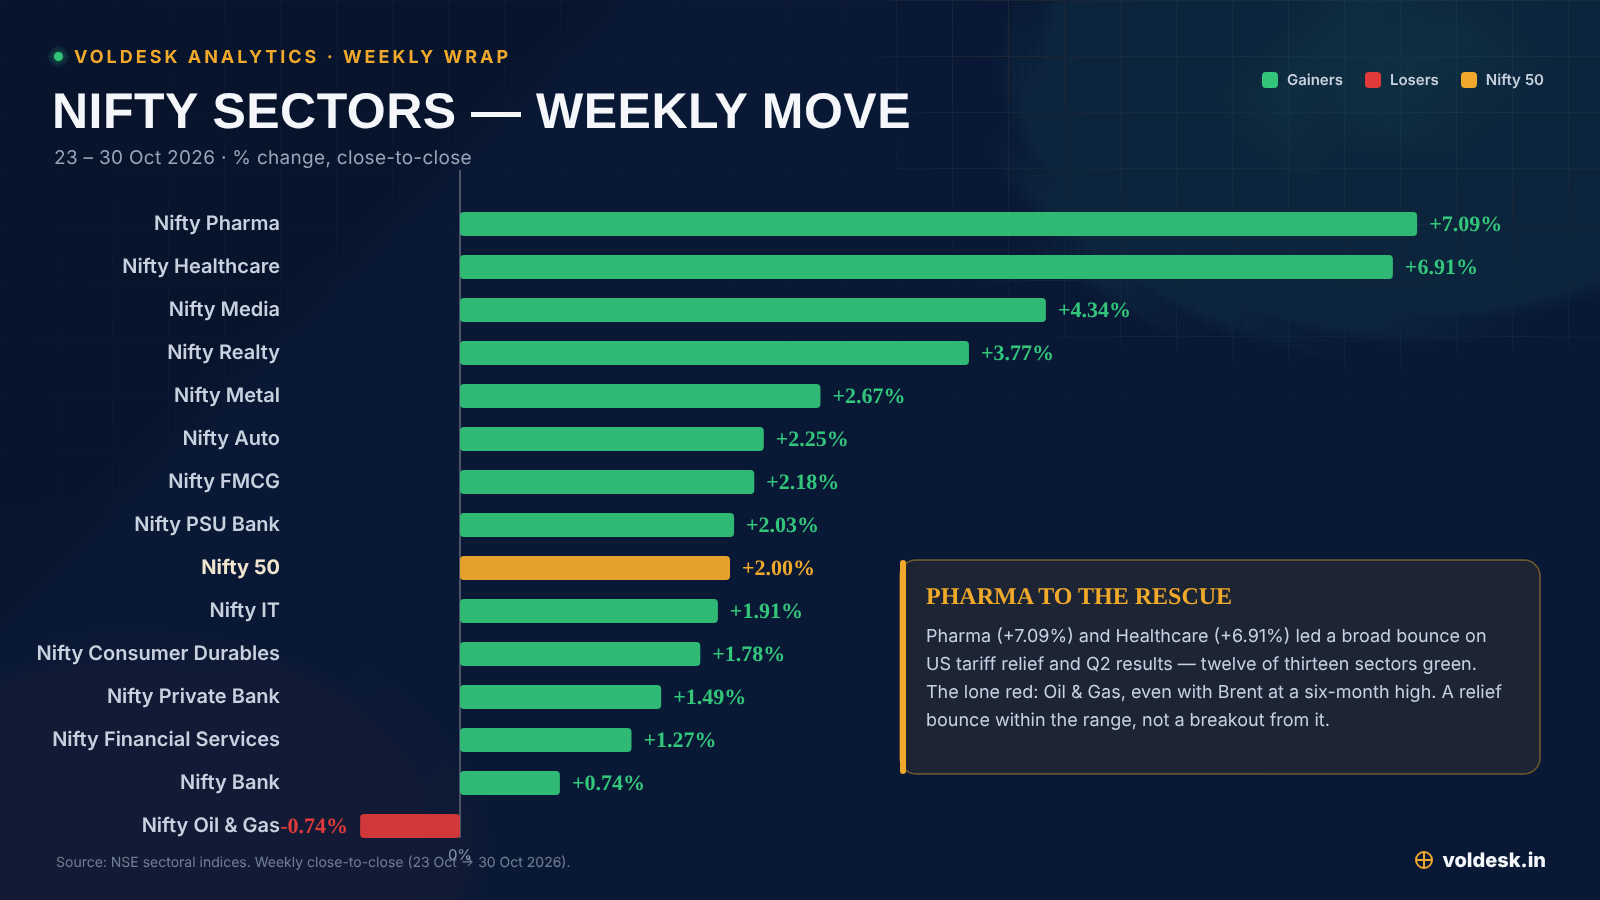
Breadth flipped back to green, with twelve of thirteen sectoral indices up, and the leadership was unusually lopsided. Nifty Pharma jumped 7.09% and Nifty Healthcare 6.91%, more than double the next sector, with Nifty Media (+4.34%), Realty (+3.77%) and Metal (+2.67%) a distant chase. The one red on the board was Nifty Oil & Gas (−0.74%), and that is telling. Even with Brent at a six-month high the oil complex couldn't hold a bid, the same pattern our crude-split spotlight flagged last week. The market keeps looking straight through a high oil price.
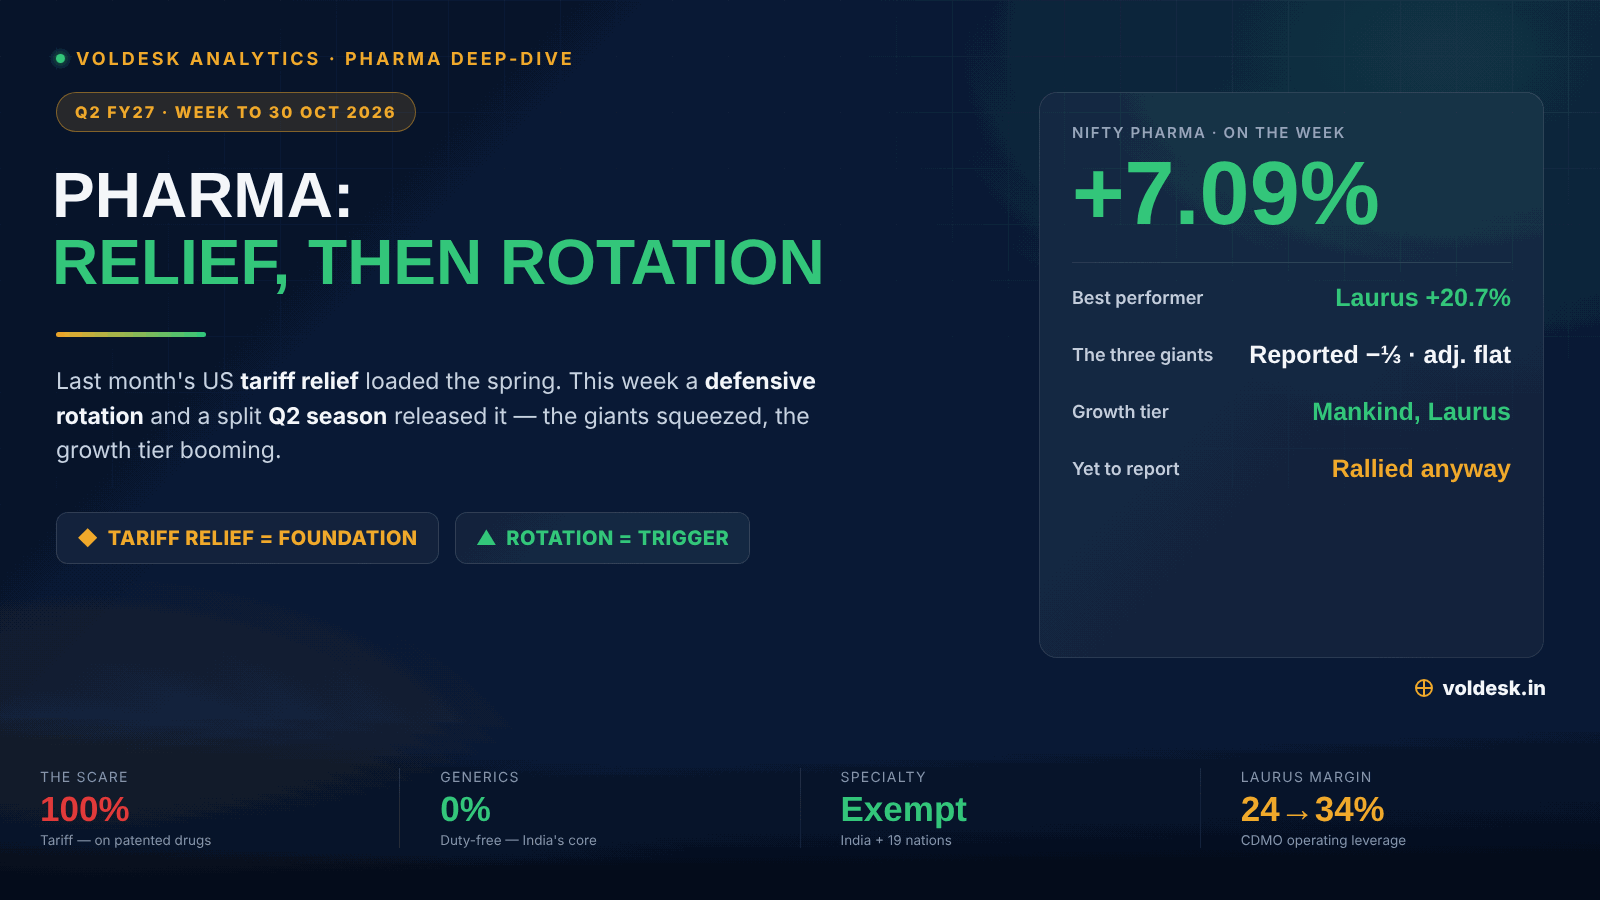
That 7% jump is not quite what it looks like. A heavyweight sector leaping while its three biggest names, Sun, Dr Reddy's and Cipla, all post headline Q2 profits down by roughly a third looks like a contradiction until you read it as a sequence. Last month's US tariff relief (specialty and rare-disease drugs exempted, India among the covered countries) had already taken the sector's biggest risk off the table. This week a defensive rotation sprang that coil, and the Q2 season did the pointing: the giants' profits fell on one-offs and base effects rather than a real slide, while the growth tier (Laurus +126%, Mankind +38%) was genuinely booming. We pull the whole thread apart in a dedicated deep-dive, Pharma: Relief, Then Rotation.
The odd part is that the rally happened in spite of the macro, not because of it. Brent sat near $117 all week, and the US Federal Reserve held rates on 29 October in a 10–2 vote where the two dissenters actually wanted a hike. A rising oil price and a hawkish-leaning Fed are not usually the stuff of rallies. The Nifty added 2% anyway, because a real, sector-specific catalyst showed up and overrode the backdrop for a week.
Nifty IT added another 1.91%, again for a non-fundamental reason. It caught a bid as a refuge from a global "AI rout", with US technology names falling on spending worries. This is the pattern to keep in mind: Indian IT now trades as a counter-trade to global AI. When sentiment around the US AI names sours, money rotates into the cheaper, AI-adjacent Indian services majors and the sector bounces, and we will see it again. But a rotation bid is not a fundamental one, and it does nothing for the problem underneath, which is flat hiring and little revenue or profit growth to point to. The bounces are real. The thesis still isn't. Over the fortnight the leadership has narrowed to four corners, Pharma, Healthcare, IT and PSU Bank, while the broad cyclical market sits in the red.
One index worth flagging away from the headlines is Nifty Chemicals. It had held the 28,000 level for about three weeks. The week before last it broke it, falling roughly 7%, and this week's 1% bounce still leaves it down ~6% over the fortnight. We read that break as structural, not noise. With Middle East supply-chain disruption and crude, the sector's core feedstock, stuck near six-month highs, both the input-cost and the logistics math have worsened. We would treat chemicals as de-rated until crude and the supply picture ease.
Spotlight: the bank split
The more durable story this week was a quieter one, inside the financials. A split is opening between public- and private-sector banks, and we read it as structural rather than a one-week quirk.
| Index | This week | Over the fortnight |
|---|---|---|
| Nifty PSU Bank | +2.03% | +1.73% |
| Nifty Private Bank | +1.49% | −2.34% |
PSU banks were one of only four green corners of the market over the fortnight, while the private names, despite a positive week, are still underwater across the same stretch. The reason, we think, sits on the deposit side of the balance sheet. In a tight-liquidity, higher-for-longer rate regime, the asset that matters most is a sticky, low-cost deposit franchise, and the government-backed PSU names have that in depth. The private banks are having to pay up for deposits, which eats into their margins. Add cheaper valuations and balance sheets that have been cleaned up over recent years, and the public-sector side looks the sturdier of the two. The risk the other way is a regime change. A sharp pickup in credit growth, or a friendlier rate surprise, tends to favour the private banks' higher-quality loan books, so this is a view tied to the current regime rather than a permanent preference.
Our forecast: the scorecard
We grade ourselves every week, and this week we got the frame right and one line wrong.
| Our view (23 Oct) | Verdict | What happened |
|---|---|---|
| The autumn range holds | Right | Third week of chop; the index is flat (−0.40%) over the fortnight. |
| Until oil cools, rallies stay on a short leash | Wrong | Oil didn't cool ($117), yet the market rose 2% on the pharma catalyst. |
| IT's move is an AI counter-trade, not a turn | Reinforced | IT rose again as a refuge from the US AI rout. |
| Oil names lag even at high crude | Consistent | Nifty Oil & Gas was the only sector in the red. |
The miss is worth sitting with. We had argued the market couldn't sustain a rally while crude stayed hot, and for a week a specific catalyst proved us wrong. The lesson isn't that oil stopped mattering. It is that a concrete, bankable trigger, here pharma's tariff relief, can override the macro for a few sessions. The range, though, we read right for a third straight week.
Macro backdrop: oil, rupee, gold, yields
The external picture barely budged, and what did move, moved the wrong way. Brent held near $117.48, still a six-month high, as Middle East risk (Saudi field attacks, Strait of Hormuz shipping, OPEC+) kept a premium baked in. The rupee slipped back above 95 to 95.08 on the heavier oil bill. Gold kept correcting, the MCX spot easing to ₹1,39,830 (down about 2% on the week and 4% over the fortnight) as the metals unwind rolled on. The Fed's hold left US yields stuck, with the 20-year near 5.36%. None of this was supportive. The market just chose to look past it.
| Asset | Level | On the week |
|---|---|---|
| Brent crude | $117.48 | Still a six-month high; Gulf risk |
| USD/INR | 95.08 | Slipped on the oil bill |
| Gold (MCX spot) | ₹1,39,830/10g | Correction rolls on, ~−2% |
| US 20-Yr Treasury | 5.36% | Flat; Fed held, hawkish tilt |
Foreign flows
The most encouraging number of the week was in the flow data. Foreign investors turned net positive in the cash market for the first time in a while, putting in about ₹6,305 crore across the five sessions, with domestic institutions alongside them at ₹3,109 crore. After months of one-way foreign outflows, that is a real shift. The caveat is the hedge. FIIs stayed net short in index futures through the week, so this looks like cautious optimism, money coming back into cash while keeping a foot on the brake, not a wholehearted turn.
Global & macro watch
- Fed on hold, hawkish tilt: rates held at 3.75–4.00% on 29 Oct in a 10–2 vote, with the two dissenters wanting a hike. No easing tailwind for EM.
- US "AI rout": US tech and AI names under pressure on spending worries, which is ironically a tailwind for Indian IT.
- Crude the swing risk: Brent above $117 on Middle East tensions keeps the inflation and rupee math uncomfortable.
- FIIs returned: +₹6,305 crore of cash inflows, but still net short in index futures.
- Pharma's tariff relief: US specialty-drug exemptions remove a real tail risk for the sector.
The week ahead
The calendar turns festive next week, with Diwali and the Muhurat trading session, a traditionally watched if symbolic start to the new Samvat. But the shape of this week's rally is the thing to read. The leadership was defensive, pharma and healthcare out front with FMCG alongside, while cyclicals and financials lagged. A bounce led by defensives is the signature of a relief rally, a flight to safety rather than a change of direction. A genuine new up-leg would be carried by banks and high-beta names, and those were nowhere near the front. For the relief to extend, we would want the other defensives, FMCG above all, to pick up the baton from here. The swing factor hasn't changed: if oil does not cool from $117, this week's gains are vulnerable, and the likeliest outcome then is the market handing some back and settling roughly flat. The levels matter too, the 23,000–23,150 band from below with 22,600 the floor. A clean break needs a bigger lever than one good week for pharma.
The bottom line
Three weeks, three big moves, and the Nifty is within a whisker of where it began. This is a range, not a trend. The lift this week was real but narrow, one sector's tariff relief and growth tier plus a tentative return of foreign money, set against a hawkish Fed and $117 oil that still cap the upside. FIIs adding to cash while shorting futures is the whole market in miniature: ready to step back in, not ready to commit. Until the macro clears or the earnings broaden, the honest read is a bounce within the range, not a break from it.
A correction to last week
One housekeeping note before we close. In last week's wrap, our crude-split table listed Apollo Tyres as up 105.74% since the 30 March low, a figure that came from a wrong base price on our side. The correct number is −8.47%. Apollo is down since March, not up, which also means it belonged with the laggards in that discussion, not the leaders. We have fixed the original piece. The error was ours and we apologise for it. Getting the numbers right is the whole job here, and we would rather flag a slip plainly than let it stand.
Keep reading
30 Oct 2026
Pharma: Relief, Then Rotation
Nifty Pharma had its best week in a long while, climbing more than 7% in the five sessions to 30 October. We only had room for a few lines o…
23 Oct 2026
Market Wrap: The Snapback Fades
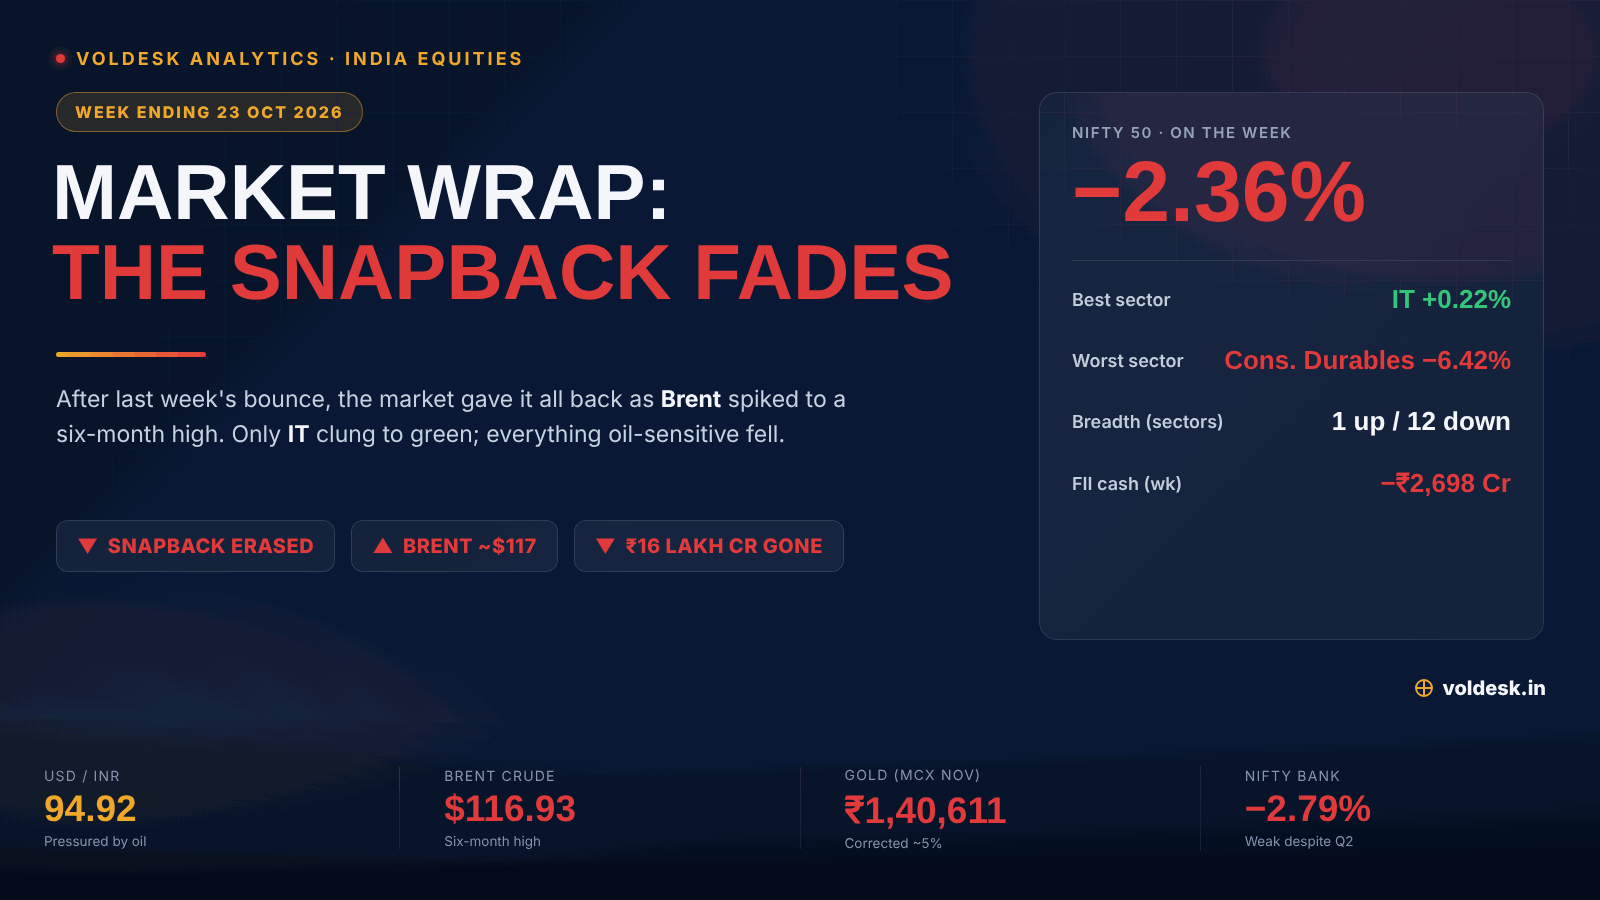
Last week we titled this column The Snapback , and warned in the same breath that it was "relief, not a verdict" — that we would not declare…
16 Oct 2026
Market Wrap: The Snapback
Two weeks ago we titled this column Nowhere to Hide — an eighth straight losing week, the Nifty at its lows, the whole market bracing for th…
Disclosure — No security recommendation. Educational market commentary. This article is for information and education only and does not constitute personalised advice. Investments in securities are subject to market risk; no returns are assured.