16 Oct 2026 · Chirag Asnani
Market Wrap: The Snapback
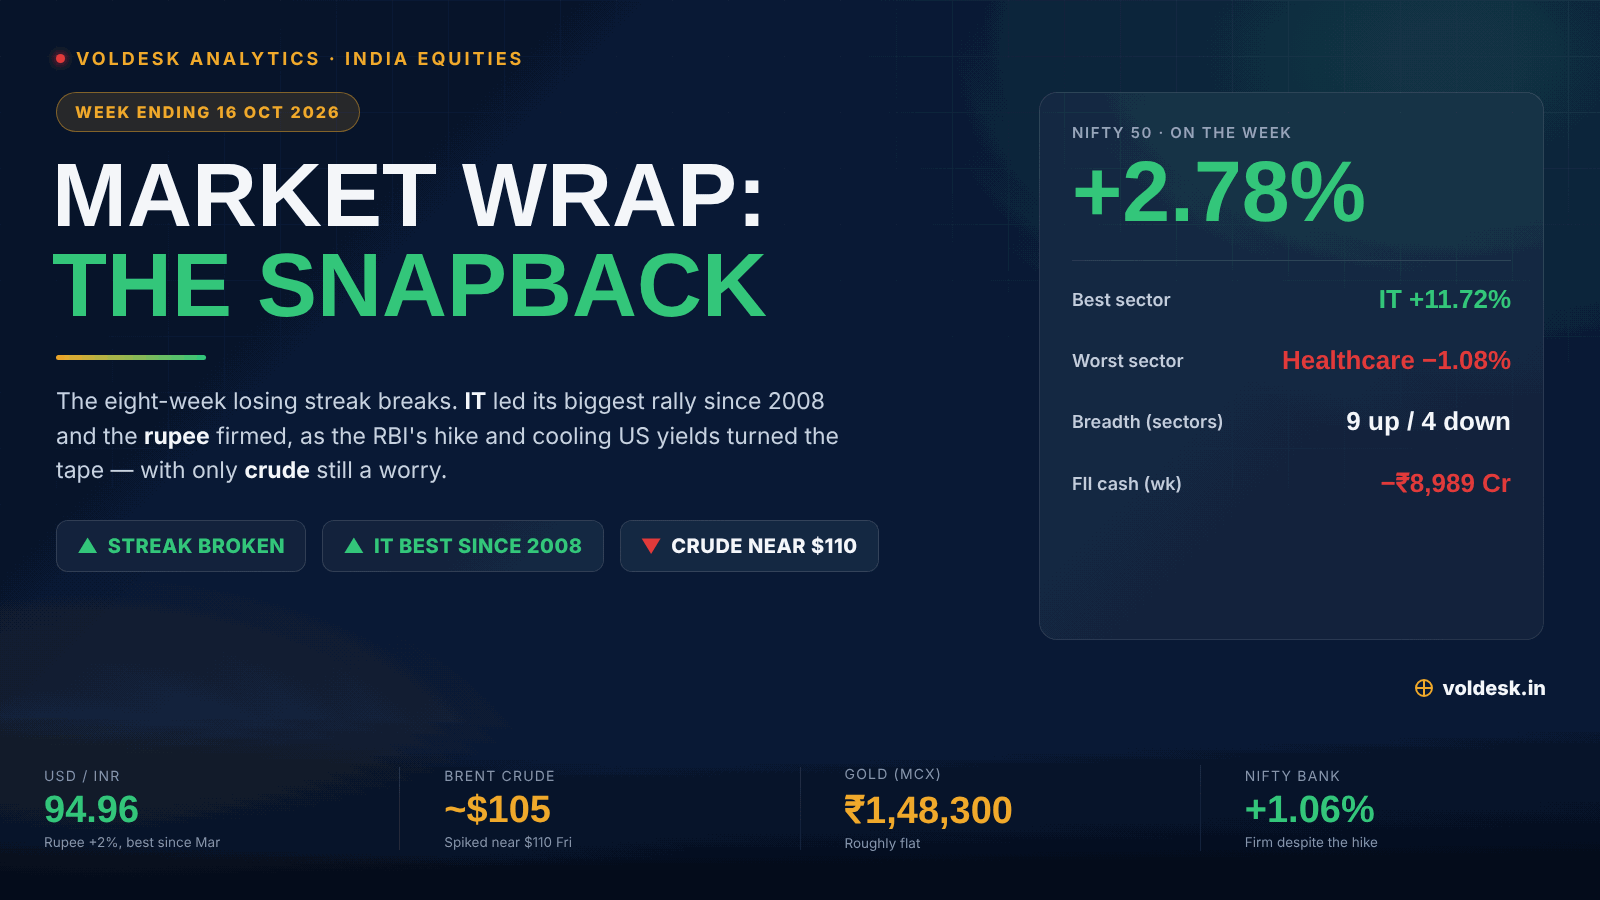
Two weeks ago we titled this column Nowhere to Hide — an eighth straight losing week, the Nifty at its lows, the whole market bracing for the RBI. We argued the market would only turn when two things changed: US yields cooling and the rupee stabilising. Both flipped, and the market turned hard. The Nifty 50 rose 2.78% to 23,146 — its second straight weekly gain and its best week since April — and the eight-week losing streak is over. The snapback was led, improbably, by the one sector we had written off a fortnight ago.
Sectors — the tape
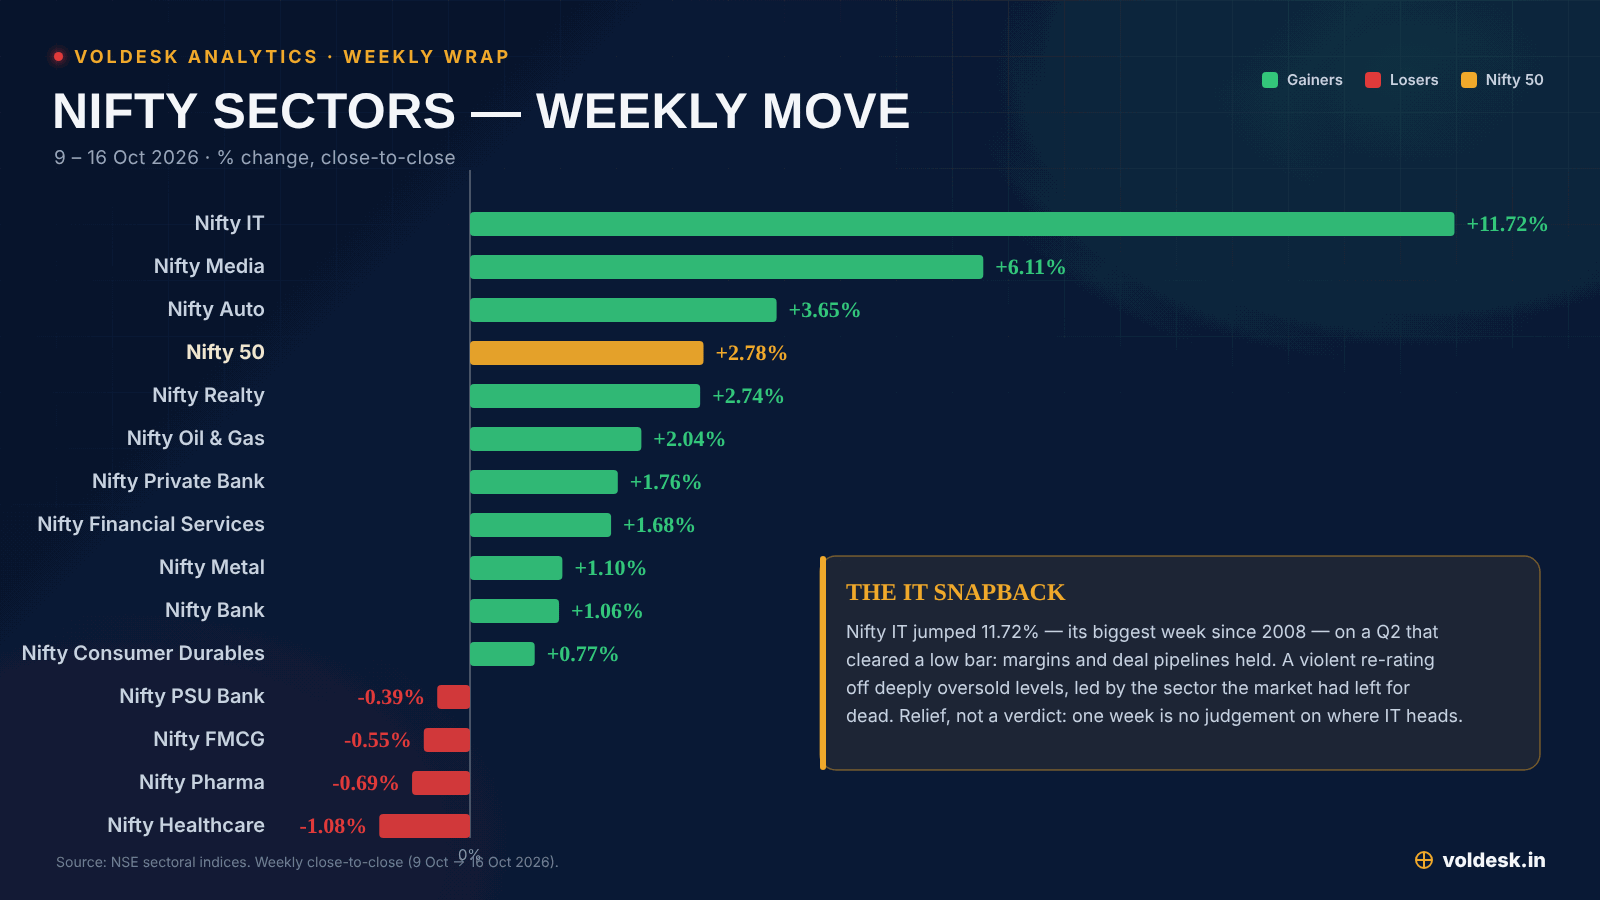
The breadth flipped hard: nine of thirteen sectoral indices closed higher, against just one two weeks ago. The leadership came from exactly the corners that had been punished hardest — high-beta and cyclical. Nifty IT was in a league of its own, up 11.72% (more on that below); Nifty Media rose 6.11%, Nifty Auto 3.65% and Nifty Realty 2.74%. The financials were firm despite a rate hike landing mid-fortnight — Nifty Private Bank added 1.76%, Financial Services 1.68% and Nifty Bank 1.06% — and Nifty Oil & Gas rose 2.04% as crude climbed.
The tell was what lagged. The defensives that were the only shelter two weeks ago were now the only red on the board: Nifty Healthcare −1.08%, Nifty Pharma −0.69%, Nifty FMCG −0.55% and Nifty PSU Bank −0.39%. Nestlé and Max Healthcare were among the Nifty's weakest names. This is the mirror image of Nowhere to Hide — money rotating out of safety and back into risk — and it is what a genuine relief rally looks like from the inside.
Spotlight: the IT majors
Nifty IT's 11.72% week was its biggest since 2008 — a near-18-year record — and it is tempting to read that as the sector turning a corner. We would be careful. This was a violent re-rating off deeply oversold levels in a sector the market had spent months leaving for dead, triggered by a Q2 that cleared a low bar rather than smashed it. Margins held, deal pipelines held, and that was enough. Tech Mahindra flagged $1.02 billion of new deal wins (up about 25% year on year); Infosys said AI services were already over 8% of revenue and growing double-digits sequentially. Resilient, yes. Re-accelerating, not yet proven.
| IT major | 9 Oct | 16 Oct | % Change |
|---|---|---|---|
| Tech Mahindra | ₹1,514.10 | ₹1,790.00 | +18.22% |
| TCS | ₹2,156.00 | ₹2,465.00 | +14.33% |
| Infosys | ₹1,023.40 | ₹1,161.20 | +13.47% |
| Wipro | ₹162.57 | ₹184.40 | +13.43% |
| HCLTech | ₹1,216.70 | ₹1,380.00 | +13.42% |
So we will say it plainly: this is relief, not a verdict. One strong week and one decent quarter do not tell us whether revenue growth is inflecting, whether discretionary demand is returning, or how AI nets out for the sector — those answers take several quarters, not one print. It is the same discipline we tried to apply on the way down, now applied on the way up: a single week does not define where IT is headed.
Our forecast: where we were right, where we were wrong
We grade ourselves every week. A fortnight ago we got the framework right and two of the specifics wrong.
| Our view (1 Oct) | Verdict | What actually happened |
|---|---|---|
| A 25 bps hike is the better outcome than a hold | Right | The RBI hiked to 5.50%; the rupee firmed 2% and the market rose. |
| The market turns when US yields cool and the rupee stabilises | Right | Both flipped — the 10-year eased to ~5.10%, the rupee to ~94.96 — and it turned. |
| Banks and financials cool off after the policy | Wrong | They firmed — Private Bank +1.76%, Financial Services +1.68% on the week. |
| IT's move was noise | Wrong | It ripped 11.72% on Q2 — though we still hold that one week is no verdict. |
Macro backdrop: oil, rupee, gold, yields
The external backdrop that drove the autumn decline has eased on every axis but one. The rupee was the headline: it firmed about 2% to ~94.96, its best week since March, as the RBI's hike and a set of liquidity and currency measures restored some confidence. US 10-year yields slipped to ~5.10%, a three-week low, as the market leaned toward a Fed hold — a world away from the two-decade highs near 5.3% that had pulled money out of emerging markets. Gold was roughly flat near ₹1,48,300 on the MCX. The exception, and it is a big one, was crude: Brent held around $105 and spiked toward $110 on Friday on supply and sanctions fears. It is the one macro variable still pointing the wrong way.
| Asset | Level | On the week |
|---|---|---|
| Brent crude | ~$105 | Elevated; spiked toward $110 Friday |
| USD/INR | 94.96 | Rupee +2%, best week since March |
| Gold (MCX active fut) | ₹1,48,300/10g | Roughly flat |
| US 10-Yr Treasury | ~5.10% | Three-week low; Fed-hold bets |
| RBI repo | 5.50% | Hiked 25 bps; "calibrated tightening" |
Foreign flows
The flow that defined the autumn fall went quiet. Foreign investors were still net negative in the cash market — ₹8,989 crore of outflows across the five sessions — but that is barely a quarter of the ₹34,966 crore they pulled in the capitulation week, and they turned net positive on Friday with about ₹1,166 crore of inflows. Domestic institutions stayed on the other side, net positive by ₹7,812 crore. The relentless foreign-investor retreat that did so much damage through September has, for now, paused — and a rally that no longer has to fight a wall of outflows is a very different animal.
Global & macro watch
- RBI hiked to 5.50%: a 25 bps move on 7 October with the stance shifted to "calibrated tightening" and no near-term cuts signalled.
- US yields eased: the 10-year back to ~5.10% as the market priced a Fed hold — the single biggest relief for EM flows.
- Crude is the swing risk: Brent near $105 and spiking toward $110 keeps the import-bill and inflation math uncomfortable.
- Rupee back below 95: a ~2% weekly gain reverses the pressure that had it testing 97.
- Q2 earnings: IT delivered; banks, autos, FMCG and the heavyweights report over the next fortnight.
The week ahead
The earnings calendar now does the talking. IT has reported; the next wave — private banks, autos, consumer names and the index heavyweights — will decide whether this rally broadens or narrows back to a handful of winners. Watch whether IT can hold its re-rating once the first euphoria fades, whether foreign inflows build on Friday's turn, and above all crude: with Brent pressing $110, the one macro all-clear we don't have is the one that feeds straight into inflation and the rupee. The new 5.50% repo rate is the backdrop for all of it.
The bottom line
This week vindicated the framework more than any single forecast: we said the market would turn when yields cooled and the rupee held, the RBI delivered the hike we argued for, and the turn came — fast. But a snapback is not the same as a new trend. The leadership came from the most oversold corner of the market on earnings that were good enough rather than great, and the one macro variable still moving the wrong way is the one that matters most for India. We are glad to see the lows hold; we are not yet willing to declare IT, or the market, out of the woods on the strength of a single, violent week.
Keep reading
02 Oct 2026
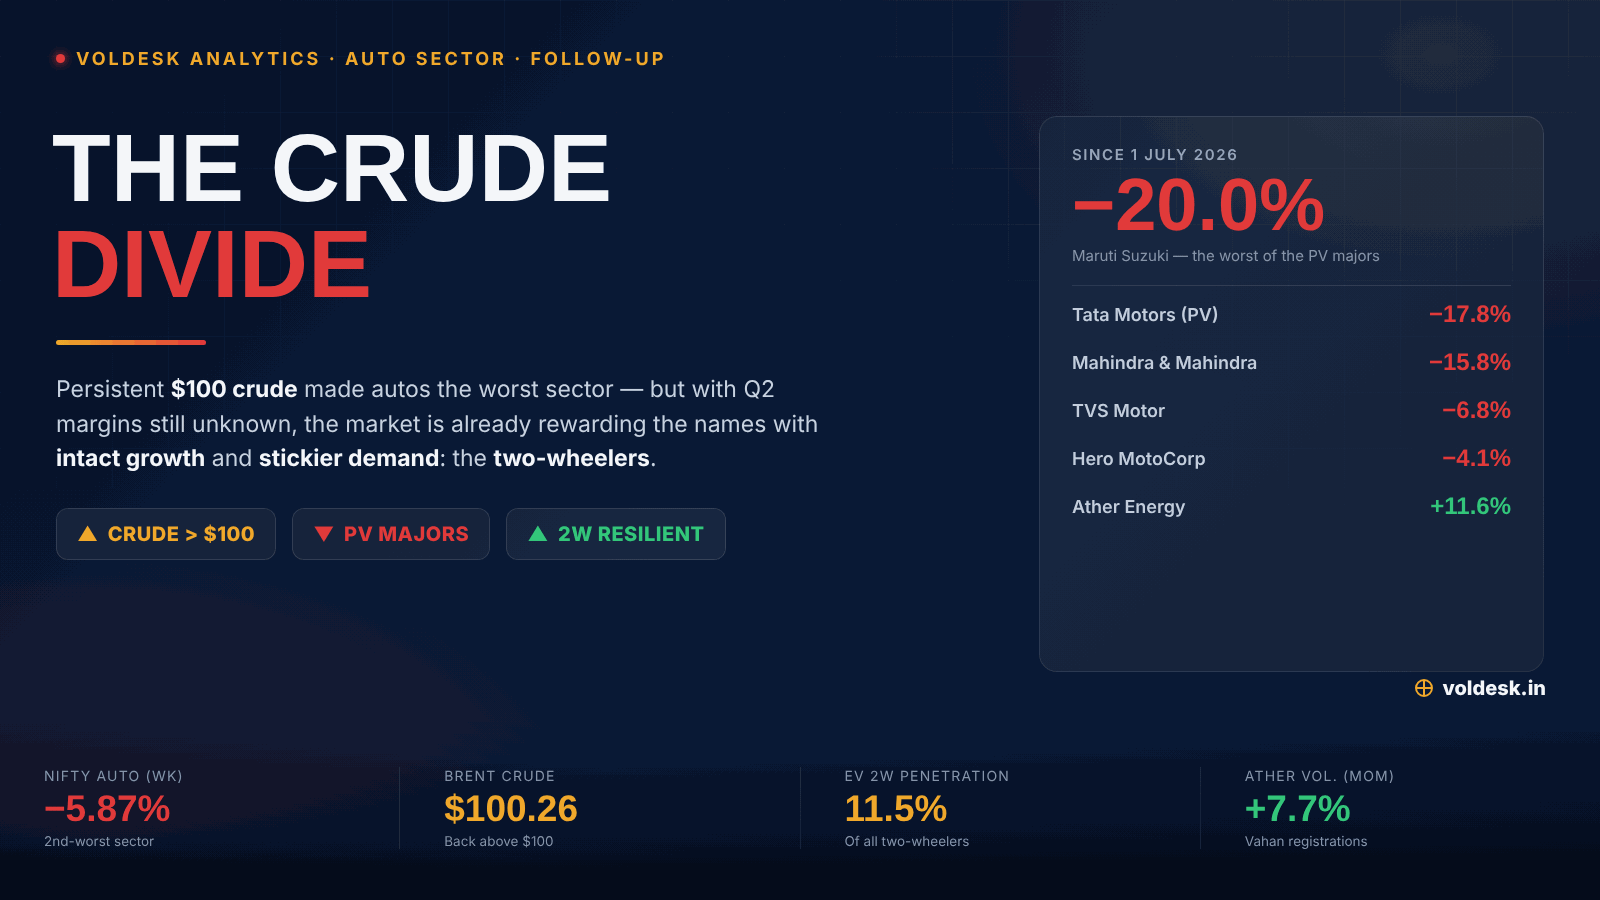
Autos: The Crude Divide
Six weeks ago, in Record Sales, Shrinking Margins , we flagged a paradox in India's auto sector: record Q1 volumes on the surface, a commodi…
01 Oct 2026
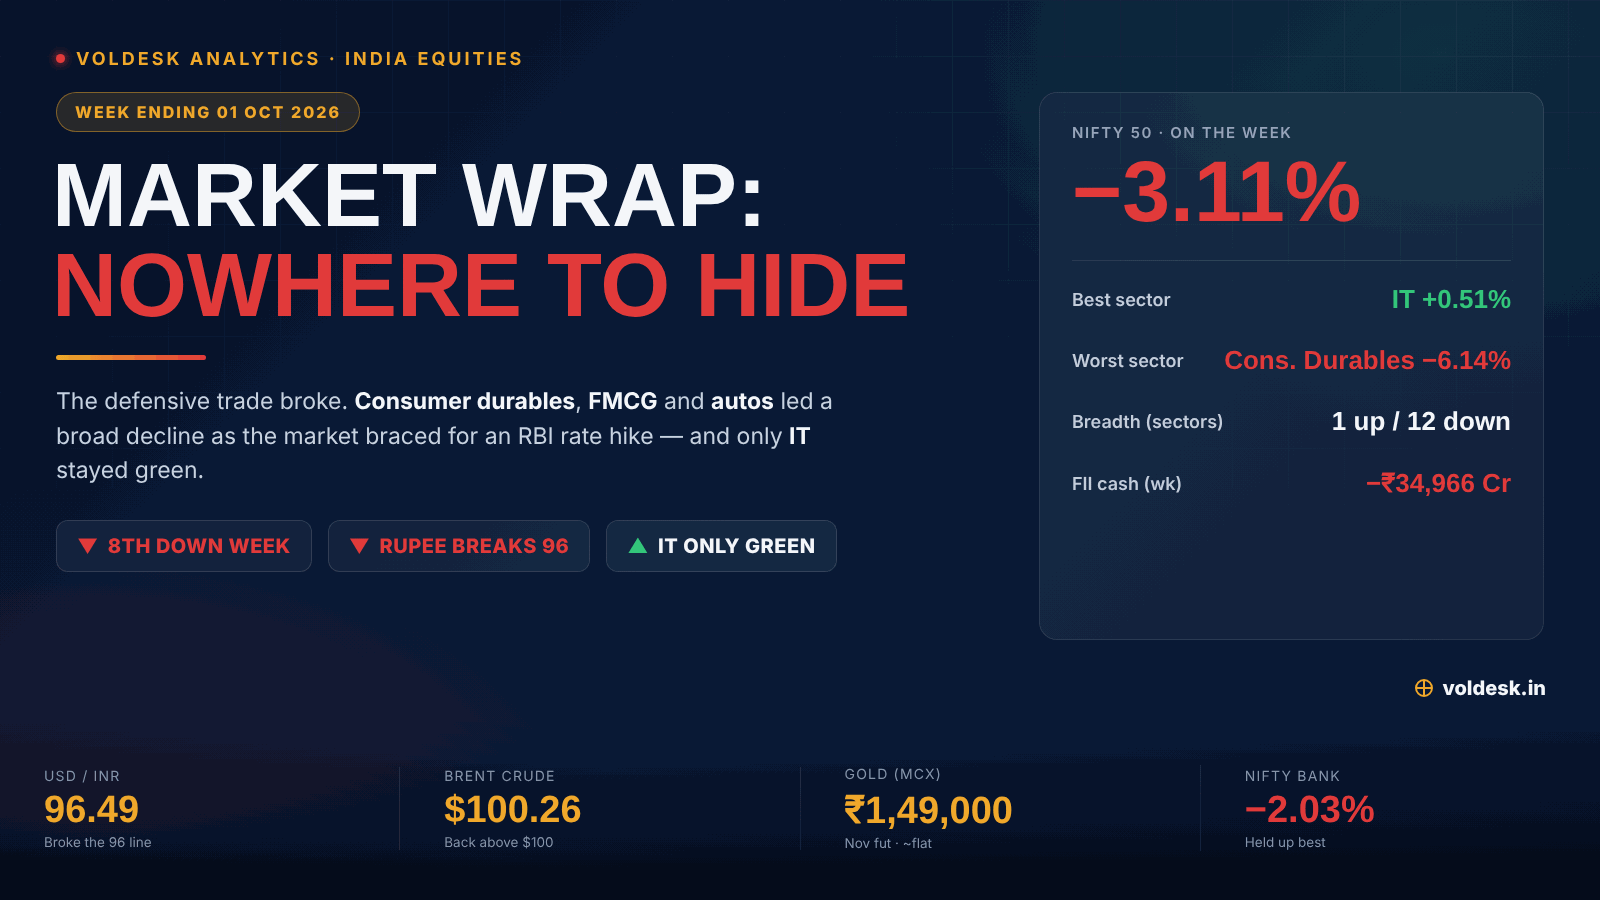
Market Wrap: Nowhere to Hide
Last week we framed it as Money Turns Defensive — money rotating out of rate-sensitive sectors into the shelter of FMCG, pharma and healthca…
26 Sep 2026
Market Wrap: Money Turns Defensive
One week after the Fed's hike, the rotation we mapped is showing up on the tape. In our post-Fed piece , we argued the move would split the …
Disclosure — No security recommendation. Educational market commentary. This article is for information and education only and does not constitute personalised advice. Investments in securities are subject to market risk; no returns are assured.