23 Oct 2026 · Chirag Asnani
Market Wrap: The Snapback Fades
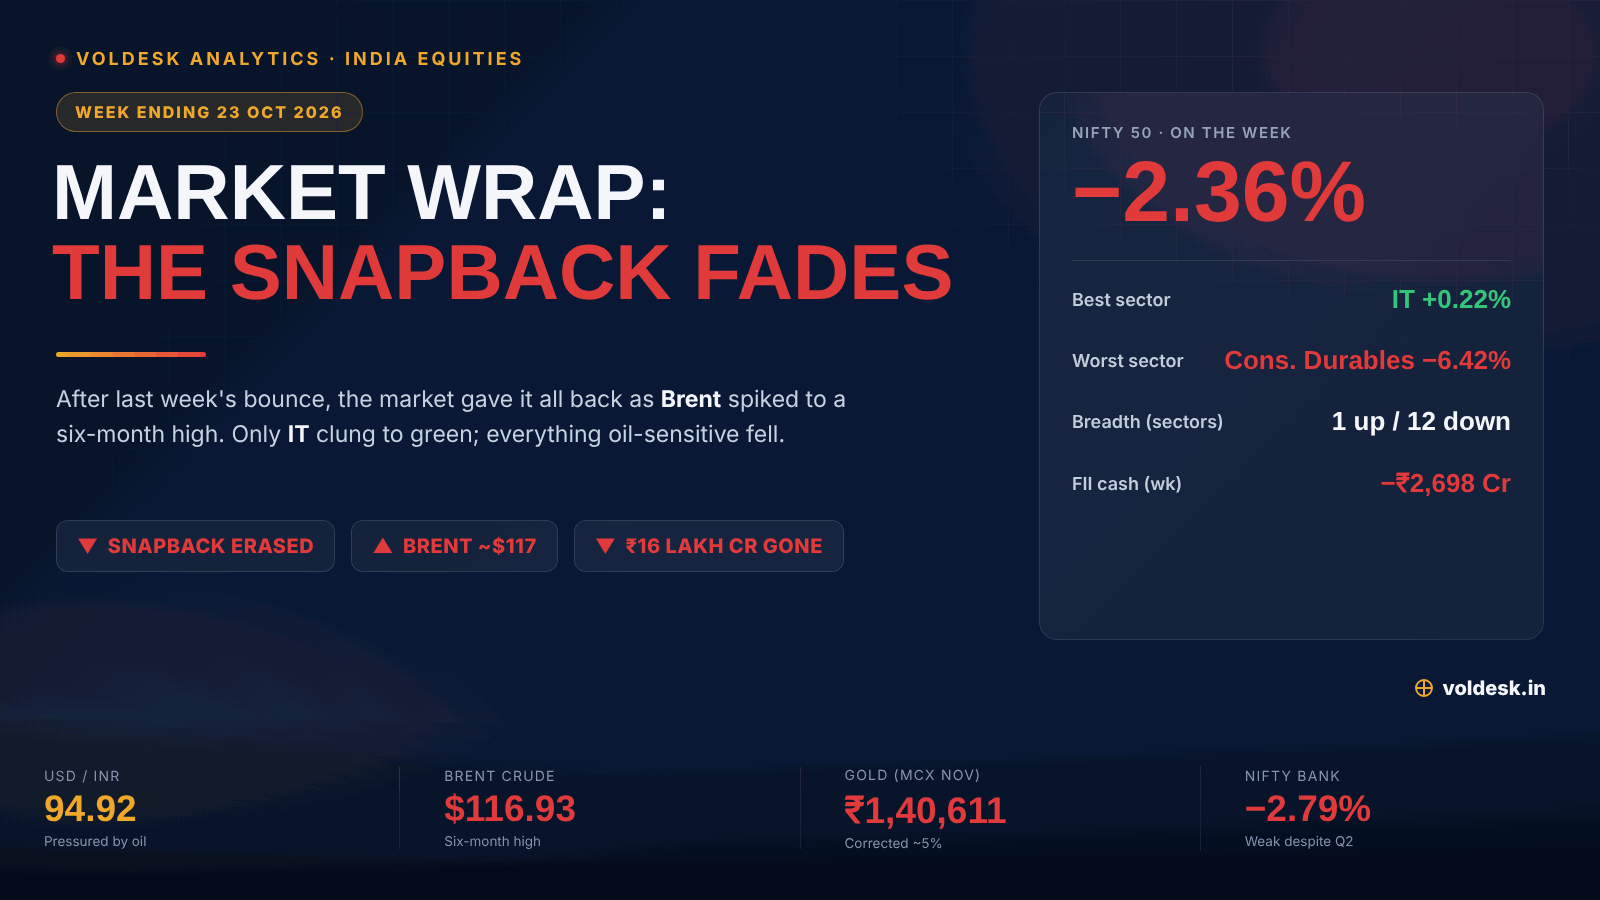
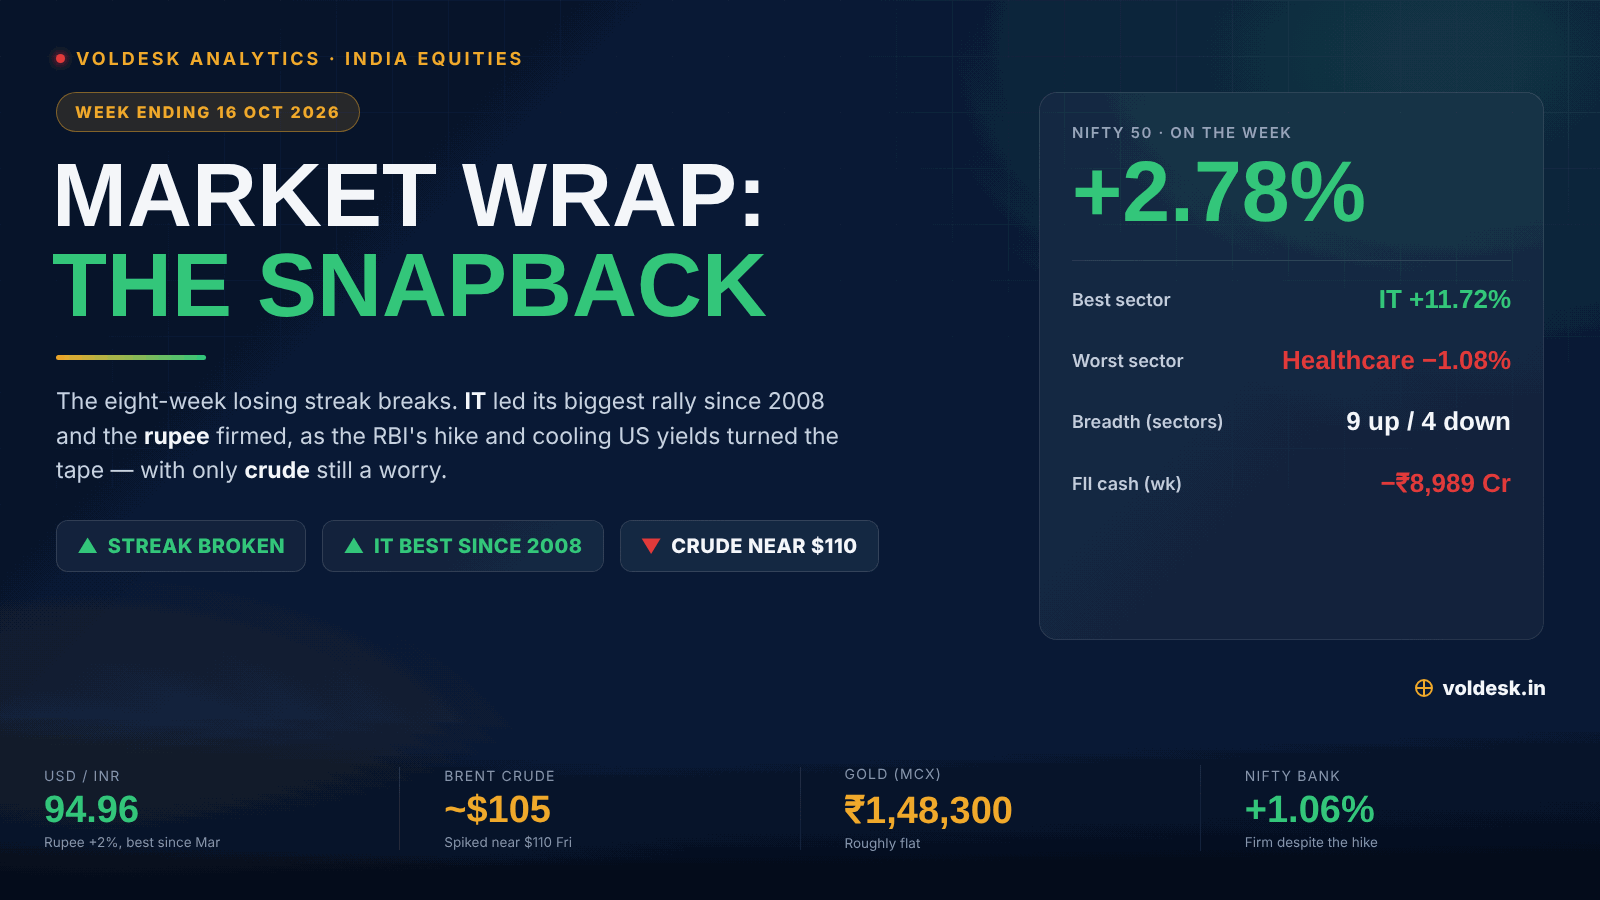
Last week we titled this column The Snapback, and warned in the same breath that it was "relief, not a verdict" — that we would not declare the market out of the woods on a single violent week, and that crude near $110 was "the one worry left." A week later, the worry arrived and the snapback faded. The Nifty 50 fell 2.36% to 22,600, handing back almost the entire prior-week bounce in four straight down days that wiped roughly ₹16 lakh crore of market value. Two weeks on from the low, the index is flat — the round trip complete.
Sectors — the tape
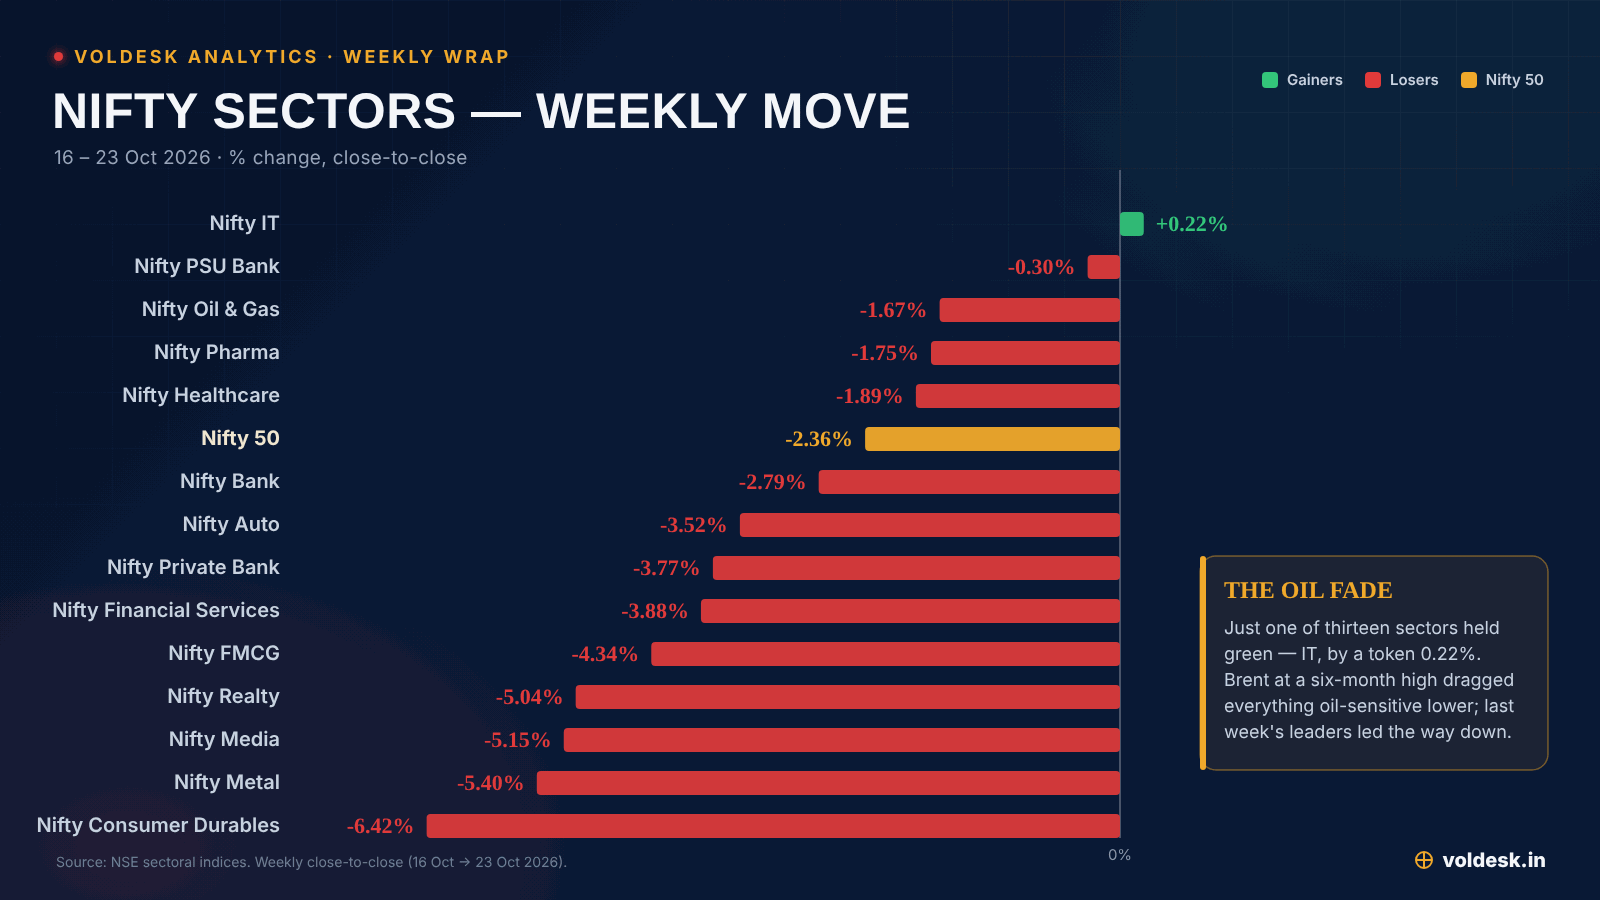
The breadth flipped straight back: just one of thirteen sectoral indices closed higher, the mirror image of last week's nine. And last week's leaders were this week's worst — Nifty Media gave back 5.15% having gained 6.11% a week earlier, Nifty Realty fell 5.04% and Nifty Auto 3.52%. The deepest cuts were in Consumer Durables (−6.42%), Metal (−5.40%) and the energy complex — all hit, directly or indirectly, by the same force: oil.
The lone exception was Nifty IT, up a token 0.22% — and even that deserves an asterisk. IT did not extend last week's 11.7% surge; it merely held it. That surge, we would argue, was never about India IT fundamentals: it was an AI counter-trade — global money rotating into cheaper, AI-adjacent tech — layered on a weak-rupee tailwind. The Q2 numbers "met expectations," but those expectations sit on the floor next to the 2022–23 boom, when the sector grew at mid-teens constant-currency rates against roughly 2–3% today. Clearing a bar set that low is not a recovery, and a 0.22% week is not a vote of confidence.
Financials stood out on the downside: Nifty Private Bank −3.77% and Financial Services −3.88%, with Nifty Bank off 2.79% — and this despite a broadly decent set of Q2 bank results. When a rising oil price is resetting the inflation and rate outlook, even clean earnings struggle to hold a bid.
Spotlight: the crude split
When crude moves this fast, it sorts the market cleanly into two camps. A high oil price is a direct tailwind for the upstream producers who realise it, and a direct headwind for everyone who burns crude or its derivatives as an input. In a week the Nifty fell 2.36%, that divide was on full display — the two upstream names we track finished higher, while every oil-consumer finished lower.
| Stock | 23 Oct | This week | Since 30 Mar |
|---|---|---|---|
| Upstream — gains on a higher crude price | |||
| ONGC | ₹227.50 | +2.48% | −20.08% |
| Oil India | ₹447.85 | +0.64% | −5.81% |
| Oil consumers — crude is a core input cost | |||
| IOC | ₹129.09 | −0.99% | −4.66% |
| Pidilite | ₹1,487.70 | −1.00% | +15.77% |
| Asian Paints | ₹2,307.00 | −1.07% | +6.55% |
| InterGlobe Aviation | ₹4,549.00 | −2.94% | +15.35% |
| MRF | ₹1,17,915 | −3.97% | −8.23% |
| Apollo Tyres | ₹374.75 | −12.65% | −8.47% |
On the week the split is clean: the two upstream producers finished higher while every oil-consumer fell, the tyre makers hit hardest through their double exposure to crude-derivatives and rubber. Apollo Tyres' 12.6% drop is too steep to be oil alone — company-specific pressure clearly amplified it — but the direction is the same across the group.
Now zoom out. Mark these same names from 30 March 2026 — the short-term bottom the market carved out during the first round of the Iran–US conflict, the last time an oil scare did exactly this — and the scoreboard flips on its head. The two "winners" are the worst performers of the lot: ONGC is down 20% since that low and Oil India down 6%. Several of the "losers," by contrast, have quietly been the leaders — Pidilite +15.8%, InterGlobe +15.4% and Asian Paints +6.6% are all comfortably higher, even if the tyre makers (MRF and Apollo, both down) are the exception that proves it is no iron law. The lesson is reaction versus trend: on the day a shock lands, the market reflexively rewards the producer and punishes the consumer; but over the cycle, crude spikes mean-revert, upstream gains rarely stick — windfall levies and a volatile oil price see to that — and the consumers whose margins compress on the way up tend to recover hardest on the way down. We have watched this exact sequence once already in 2026. This spike is round two.
Our forecast: where we were right
Last week's caution reads well seven days on.
| Our view (16 Oct) | Verdict | What happened |
|---|---|---|
| The rally is relief, not a verdict | Right | It faded inside a week; the index round-tripped to flat. |
| Crude near $110 is the one worry left | Right | Brent spiked to ~$117, a six-month high, and drove the fall. |
| Q2 earnings decide if the rally broadens or narrows | Narrowed | Decent bank results couldn't offset the macro; financials fell. |
| IT's jump was a re-rating, not a fundamental turn | Holding | IT stalled at +0.22% as the AI counter-trade faded. |
Macro backdrop: oil, rupee, gold, yields
This was a one-variable week, and the variable was crude. Brent spiked to nearly $117 a barrel — a six-month high — after a drone attack on Saudi Arabia's Shaybah oil field, a US withdrawal of non-emergency Gulf staff, and renewed fear of escalation involving Iran. A higher import bill fed straight into the rupee, which gave back its earlier gains to end near 94.92. Gold, counter-intuitively, did not rally on the tension — it corrected about 5% to ₹1,40,611 on the MCX November future, with silver crashing over 4%, as the haven bid flowed into oil rather than bullion. US 10-year yields slipped below 5% to about 4.98%, helped by a wobble in US tech and softer Fed-hike odds ahead of the 28–29 October FOMC — a relief that oil comfortably drowned out. The RBI's repo rate sits at 5.50%.
| Asset | Level | On the week |
|---|---|---|
| Brent crude | ~$116.93 | Six-month high on Gulf tensions |
| USD/INR | 94.92 | Gave back gains on the oil bill |
| Gold (MCX Nov fut) | ₹1,40,611/10g | Corrected ~5%; silver −4%+ |
| US 10-Yr Treasury | ~4.98% | Slipped below 5%; FOMC 28–29 Oct |
Foreign flows
Here is the twist: this was not a foreign-investor exodus. FIIs were net negative by just ₹2,698 crore across the four sessions — and net positive on two of them — while domestic institutions added ₹10,941 crore. On net, institutions put far more in than they took out. The pressure that pushed the market lower came from elsewhere: the mega Jio Platforms IPO, subscribed 13.8 times, drained a wall of liquidity from the secondary market, and sentiment around the oil shock did the rest. The domestic bid is intact; this was a macro shock, not distribution.
Global & macro watch
- Crude at a six-month high: Brent near $117 on Gulf tensions is the single swing factor for this market right now.
- Rupee under pressure: back near 94.92 as a heavier oil import bill undoes the prior week's gain.
- US Fed, 28–29 Oct: the 10-year slipped below 5% (~4.98%) on softer hike odds and a US tech wobble — the decision is the next global cue.
- Gold & silver corrected: the haven bid went to oil, not bullion — gold ~−5%, silver −4%+.
- Flows held: FII outflows were minimal (−₹2,698 cr); DIIs added ₹10,941 cr — the domestic bid did its job.
The week ahead
Everything routes through oil. A cooling in crude or a de-escalation in the Gulf is the fastest path back up; a further spike is the opposite. Beyond that, watch the 28–29 October FOMC, the last of the Q2 results, the 22,400–22,500 support zone on the Nifty, the Jio listing, and the approach of the Diwali and Muhurat trading season. With a 56.7 composite PMI and the domestic bid intact, the floor looks domestic; the ceiling, for now, is set in the oil market.
The bottom line
The autumn range holds. The snapback and its fade have cancelled out, and two weeks on the index sits where it began — because the home picture never justified either the panic or the euphoria. What is moving this market is one external variable: the price of crude, and the geopolitics behind it. Until oil cools, rallies will stay on a short leash — and if March is any guide, when it does cool the lead comes from the names crude is punishing today, not the handful it is rewarding. The IT "comeback," meanwhile, keeps looking more like an AI counter-trade than a change in the weather.
Keep reading
30 Oct 2026
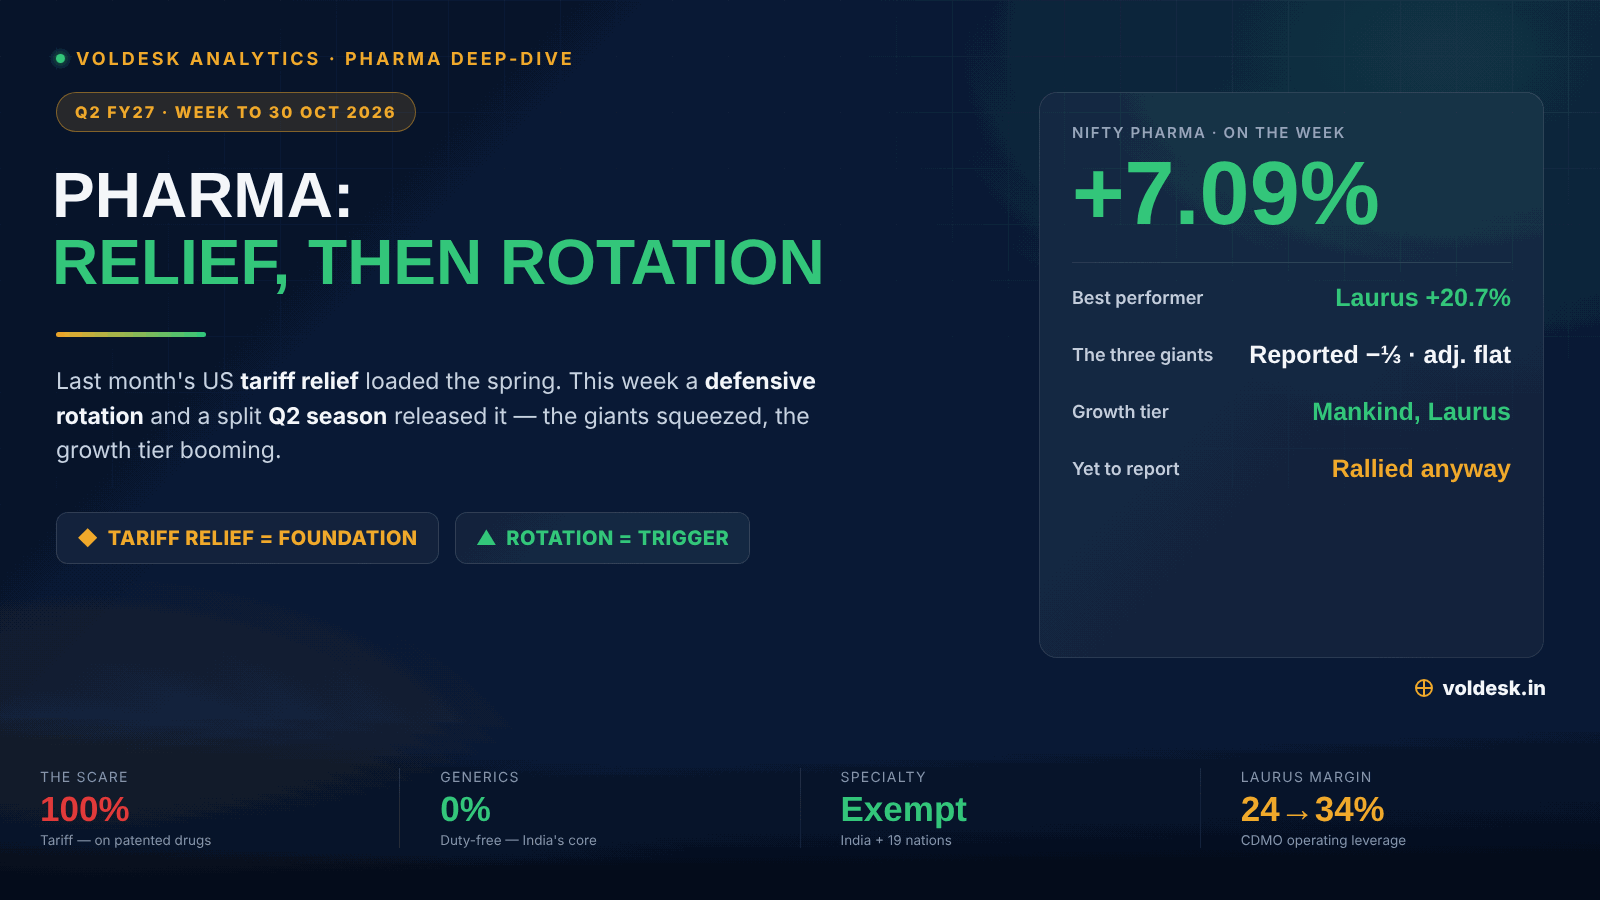
Pharma: Relief, Then Rotation
Nifty Pharma had its best week in a long while, climbing more than 7% in the five sessions to 30 October. We only had room for a few lines o…
30 Oct 2026
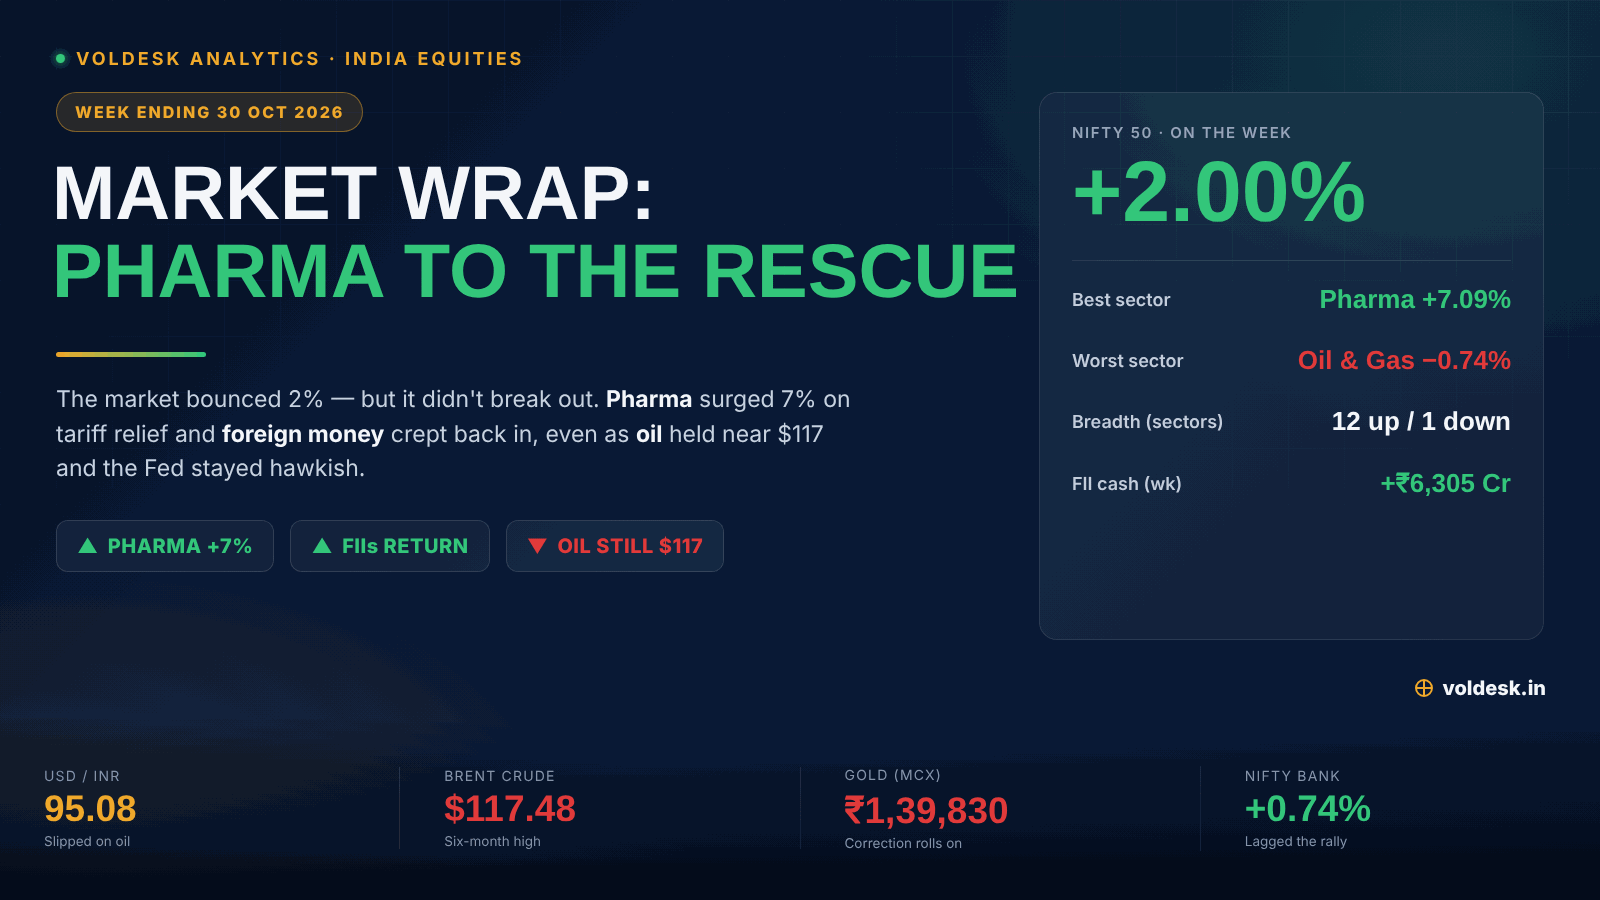
Market Wrap: Pharma to the Rescue
For the third week running, the market moved a lot and went almost nowhere. After The Snapback and The Snapback Fades , this week was the bo…
16 Oct 2026
Market Wrap: The Snapback
Two weeks ago we titled this column Nowhere to Hide — an eighth straight losing week, the Nifty at its lows, the whole market bracing for th…
Disclosure — No security recommendation. Educational market commentary. This article is for information and education only and does not constitute personalised advice. Investments in securities are subject to market risk; no returns are assured.