09 Sep 2026 · Chirag Asnani
Tempsens: The Manufacturing-Leader Premium, Already Priced In?
Tempsens Instruments (India) priced its IPO at ₹300 — roughly 35x earnings — listed on 28 August 2026 and closed its first day at ₹586.65, a 96% pop. It has since eased to around ₹546, still nearly double the issue price. The business did not transform in three weeks; the multiple did — from the mid-30s to roughly 61x. For anyone holding an allotment or weighing fresh money, the real question isn't the listing gain. It is whether the premium the market pays a manufacturing leader is earned here, or already fully in the price.
A genuine manufacturing leader
Start with what is not in dispute: this is a quality franchise. Tempsens is India's largest maker of contact and non-contact temperature sensors (~10.5% domestic share), and adds specialty cables and heating solutions — industrial furnaces and heaters — from 13 manufacturing units (ten in Udaipur, three overseas). It sells into steel, petrochemicals, power, glass, defence and nuclear, split roughly two-thirds Projects/OEM and one-third recurring MRO replacement demand. The numbers back the label: FY26 revenue of ₹445 crore (a ~27% three-year CAGR), a 24.8% EBITDA margin, 21.6% return on capital, exports near 28% of sales, and a notably clean balance sheet at 0.15x debt-to-equity. Quality is not the debate. Price is.
Why India is paying up for manufacturing
There is a coherent, well-grounded case for why a name like this commands a rich multiple, and it deserves a fair hearing. Indian public markets have, for several years, awarded scarce, high-return manufacturing leaders a persistent premium — the market pays for pedigree, dominant share and pricing power, because there are few clean ways to own them. Three structural forces reinforce that today:
- The macro tilts their way. India's current-account deficit is running low — around 1% of GDP — while the rupee sits near record lows against the dollar. A weaker rupee makes domestic manufacturing more competitive against imports and lifts export realisations. A company that exports ~28% of output and substitutes imports at home is structurally on the right side of both trends.
- Policy is pushing the same direction. Production-Linked Incentive (PLI) schemes, Make-in-India and a broad capex cycle in defence, nuclear, power, electronics and EVs are lifting exactly the end-markets Tempsens' sensors, cables and heating systems feed. It is not a direct PLI recipient, but it is a clear picks-and-shovels beneficiary of that spending.
- Leadership compounds. Multi-year customer qualification cycles, an installed base that pulls recurring MRO demand, and a rising export book give a category leader durability that the market is willing to capitalise into a high multiple.
Put together, these explain why sentiment toward domestic manufacturing leaders is strong — and why the market did not hesitate to re-rate Tempsens sharply on listing.
How the market rewarded a comparable leader
The cleanest evidence for how India prices a manufacturing leader is Indo-MIM, which listed just weeks earlier. The parallels are close — near-identical ~25% EBITDA margins and ~22% returns on capital, global customers, market leadership (Indo-MIM is the world's #2 in metal-injection moulding). It priced at ~45x, drew a 72x subscription, listed 44% up, and has since traded up toward ~71x trailing. In other words, the market has been willing to pay 45x at issue rising to roughly 60–70x in the aftermarket for precisely this profile.
Measured against that yardstick, Tempsens at ~61x is not an outlier — if anything it screens as the cheaper, less-leveraged of the two, for a similar return profile. That is the strongest single argument that the premium here is a category norm rather than an aberration.
What the premium already asks
The counterweight is equally honest. At ~₹546 the stock carries these multiples:
| Measure | At ~₹546 | Context |
|---|---|---|
| Trailing P/E (FY26, adjusted) | ~61x | IPO was priced at ~35x |
| Forward P/E (FY27E) | ~50x | on ~₹11 adjusted EPS |
| EV / EBITDA (FY26) | ~41x | against a 0.15x debt/equity balance sheet |
| Price / Book | ~7x | on post-issue net worth |
Two things are worth keeping straight. First, reported earnings understate the business slightly — the Marathon Heater amalgamation brought intangible amortisation that depresses reported profit, so the adjusted ~61x is the fairer read (and still full). Second, the ~82% gain since the ₹300 issue is almost entirely multiple expansion, not earnings growth — the company has not doubled its profit in a fortnight. Rich multiples on good businesses have a long habit of normalising through time — the stock going sideways while earnings catch up — as often as through a fall. At ~61x on ~30% growth, the PEG is close to 2x: the tailwinds have to keep delivering for the premium to hold.
Leader's premium, or priced-in?
Both halves of this are true at once. Tempsens is a real manufacturing leader with genuine structural wind at its back — the macro, the policy push and the market's standing appetite for scarce, high-return manufacturers all argue for a premium, and the Indo-MIM parallel shows that premium is exactly what comparable leaders have been granted. Equally, ~61x already banks a good deal of that optimism, and the post-listing move has been the multiple re-rating rather than the earnings arriving.
The frame differs by seat. A listing-day allottee is sitting on a gain that is now valuation-driven, and the question is how much of it to treat as durable. Fresh money pays the full premium at the door and needs the growth and the tailwinds to keep compounding to be rewarded from here. Neither is a verdict — those depend on your horizon and your own discipline on price. The most useful exercise is to separate the two questions the market has fused: is this a great manufacturing business (the evidence says yes), and what is that leadership worth to you today (that one, only you can answer).
References & further reading
- Tempsens Instruments (India) Limited — Red Herring Prospectus, dated 14 August 2026 (Financial Information; Basis for Offer Price; Our Business)
- Indo-MIM Limited — prospectus and post-listing market data, for peer context
- Reserve Bank of India — current-account balance releases, FY26
- chittorgarh.com/ipo/tempsens-instruments-india-ipo/2668/ — issue structure and listing data
- screener.in — for ongoing financial updates
Keep reading
20 Sep 2026
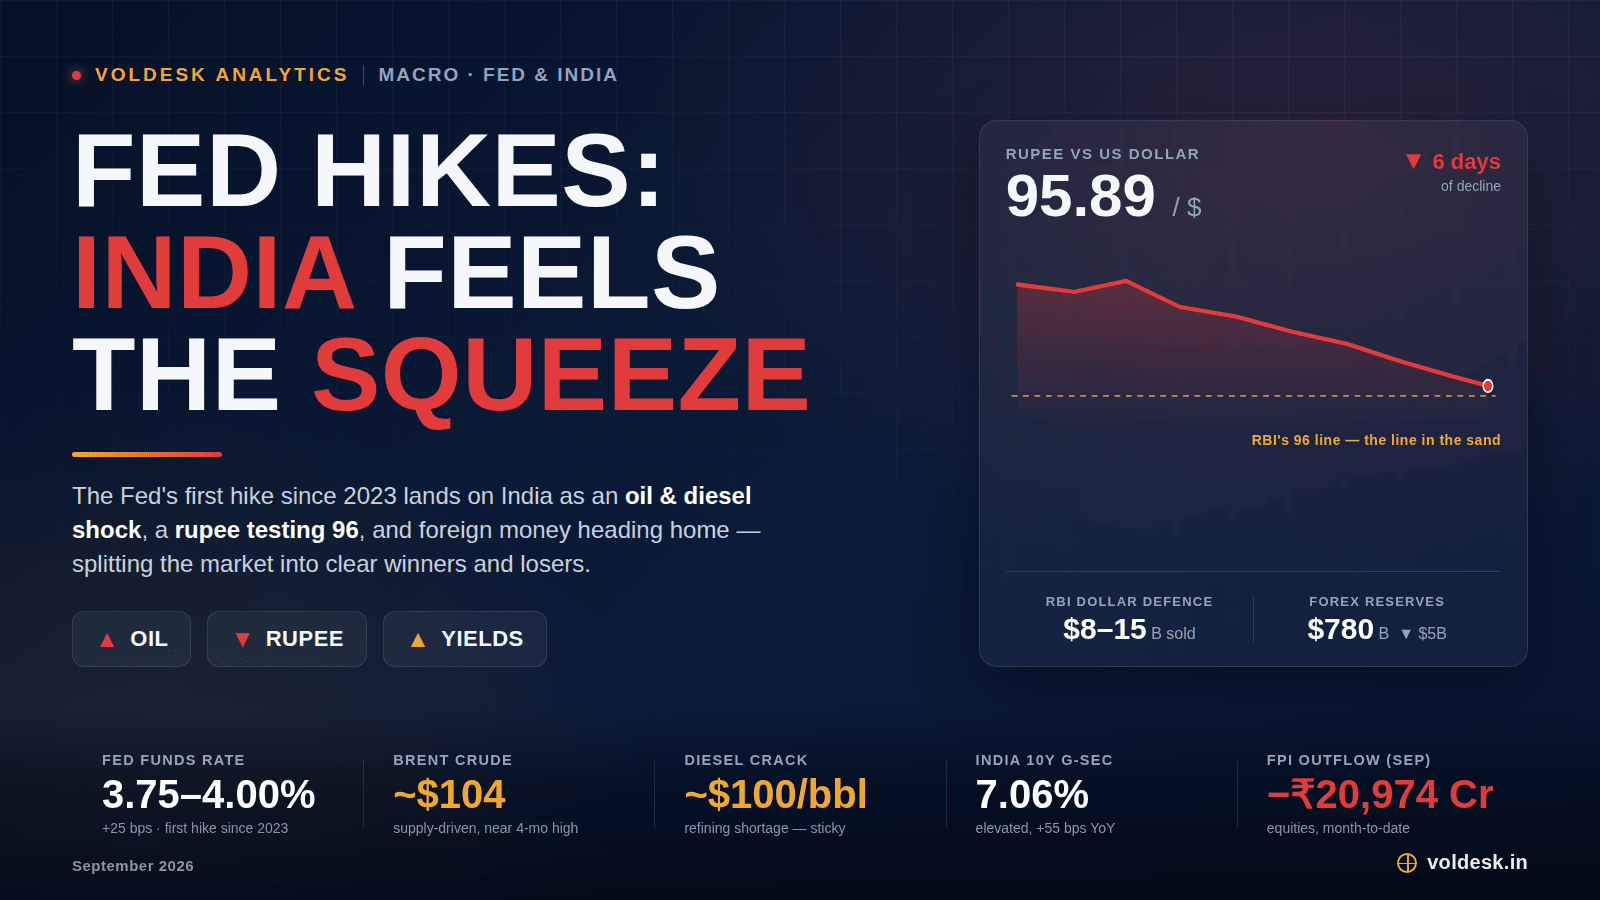
Fed Hikes: India Feels the Squeeze
On September 16, 2026, the Federal Reserve raised its target range by 25 basis points to 3.75% – 4.00% — its first hike since 2023. The trig…
09 Sep 2026
Rentomojo: India's First Listed Rental Play — Good Company, Fair Value?
For the first time, Indian public markets get to price a furniture-and-appliance rental platform . Rentomojo Limited opens its ₹1,256 crore …
30 Aug 2026
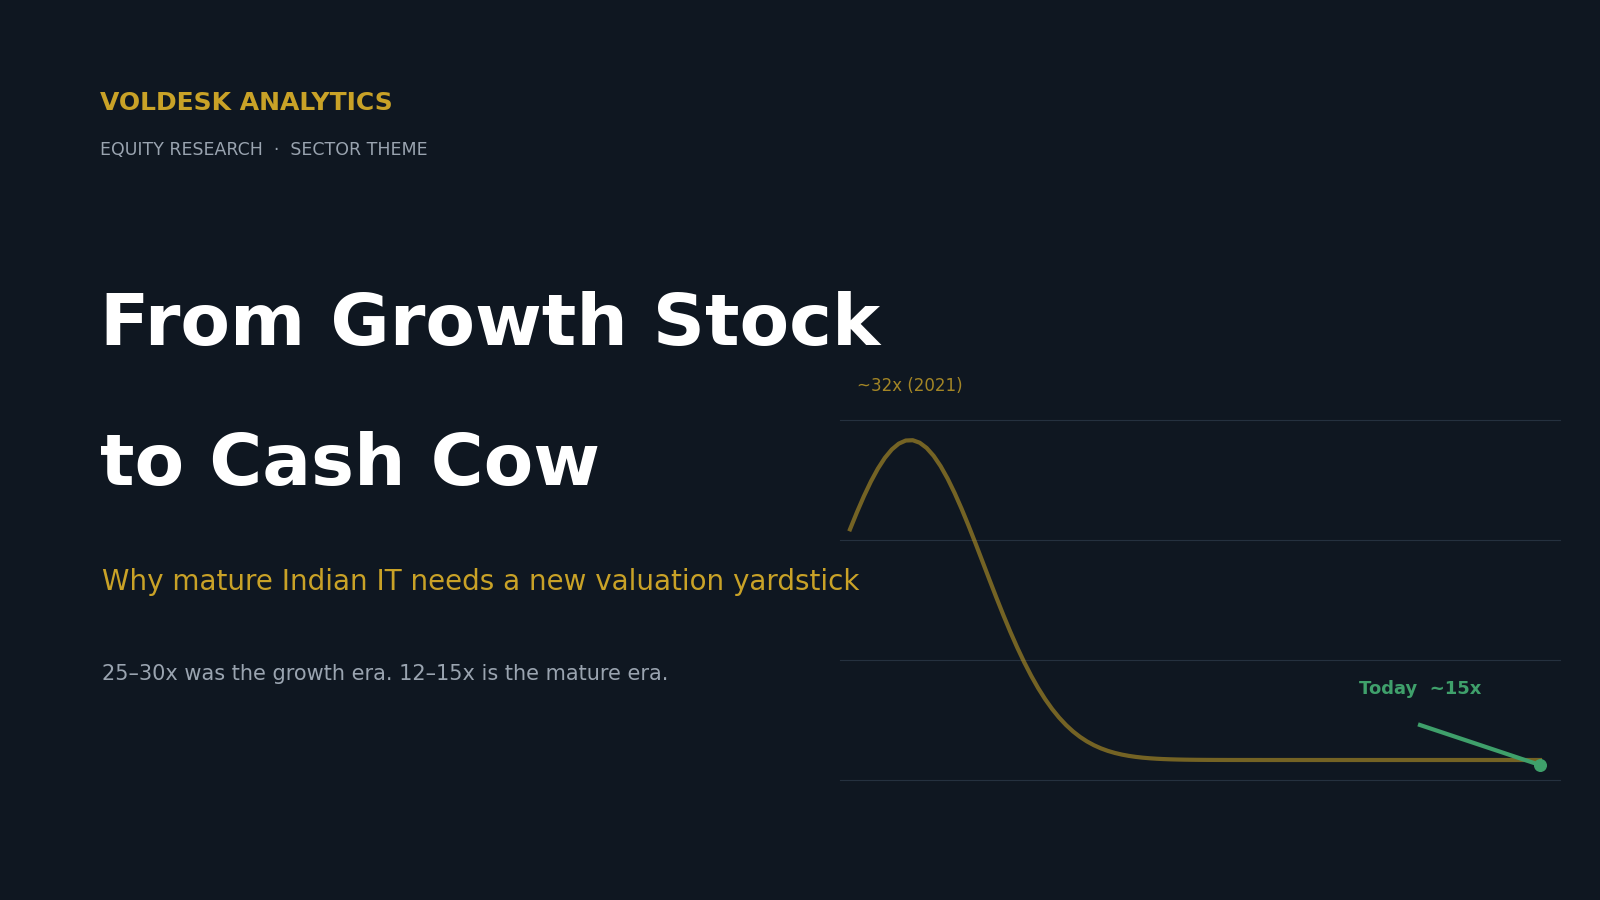
Indian IT: From Growth to Cash Cow
For fifteen years, Indian IT services was the market's dependable growth machine, and investors paid for it accordingly. Through most of the…
Disclosure — Educational market commentary only. Not a recommendation to deal in any security. Figures are drawn from the company prospectus and public sources as at the date of publication and may change. This article is for information and education only and does not constitute personalised advice. Investments in securities are subject to market risk; no returns are assured.